Start Here
A roadmap of systematic trading: 17 stations from theory to live trade, 835 quant strategies with named edges, and a free 65-page PDF. Start with one question: who pays you?
A thread quotes a 71% win rate for fading bitcoin funding. A bank note says buy AUDJPY for the yield. On $100,000, a 4% gap between Australian and yen rates is about $4,000 a year, and a normal day moves the pair by roughly fifty times that paycheck. Into 2008 the gap had been near 7% a year, and AUDJPY then lost nearly half its value in about three months. The paycheck was the premium for warehousing that crash. The person forwarding either pitch usually cannot name the payer, or the date the payer stops.
This page is the web version of The Quant Map: the map's own stations, numbered and named as on the plate, each with the articles that answer it. Pick the question you cannot answer about a trade you already have, and read that row. A blank link means the piece is written and queued. The printable PDF carries the plate in vector, five worked descents (example research from observation to live rule), and the full 835-entry strategy library. It waits at the end of the page.
Keep four words apart. A theory explains why someone pays. A feature is a number you could have computed that morning. A strategy turns the number into a repeated decision, with a size and a wrapper. A factor asks the same question across a universe. Between the feature and the strategy sit a forecast, a threshold, and a cost check. Any one of those can zero the trade.
The grand map
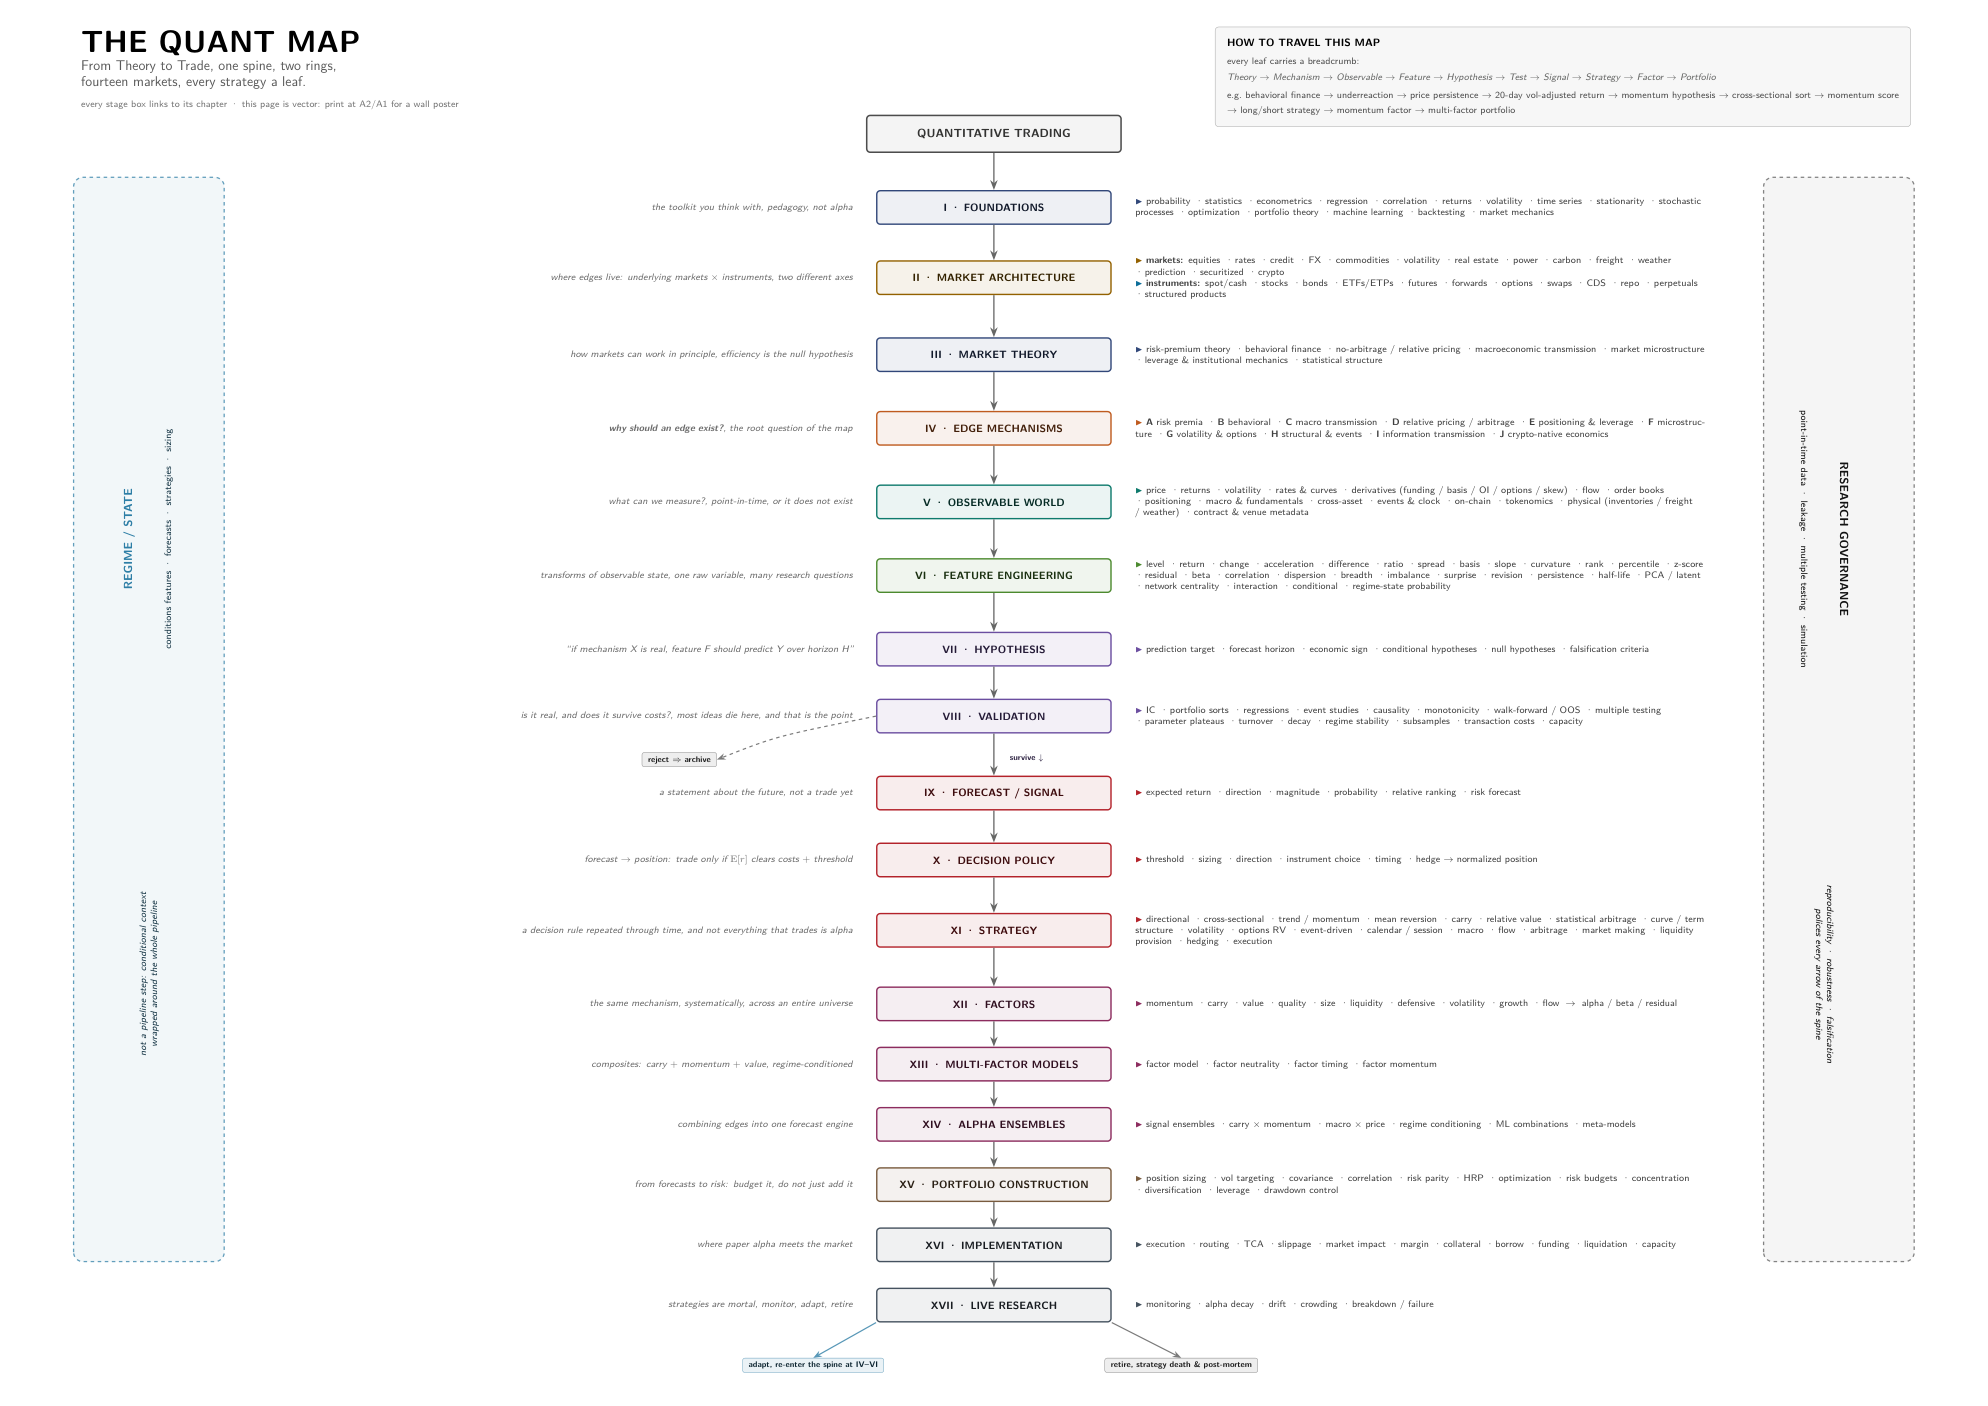
Every box on the plate is a section of this page. Open the plate full size to read it closely. The PDF at the end of the page carries the same plate as a vector A2 sheet, printable for the wall.

The spine, stage by stage
Seventeen stations, numbered and named as on the plate. Find the station where your trade broke, or walk them in order and stop at the first one you cannot pass.
I · Foundations
the toolkit you think with, pedagogy, not alpha
A strategy that wins 55% of trades still hits eight losers in a row about 0.17% of the time, once or twice per thousand trades. That run is the strategy working. Risk 2% of a $5,000 account and the streak costs about $800. Risk 15% because the setup looked clean and the same streak is the account. A second trap sits in the average: +60% then −40% advertises +10% a year, and $100 becomes $96. Compounding pays the variance. The average does not.
| Article | Why it is on this row |
|---|---|
| Why Trading Is a Probability Business, Not a Certainty Business | One trade is one draw. The standard deviation of trade returns runs several times the edge, so the signal shows up through sample size. |
| Fat Tails: Why Gaussian Thinking Breaks Trading Systems | The streak table gets worse once the left tail is fatter than a normal curve. Gaussian size is how the account dies on an "ordinary" day. |
| Get-Even-Itis: The Most Expensive Disease in Trading | The streak is when you edit the size. The calm version of the rule has to be the one that is already written. |
| Average Drawdown vs Extreme Drawdown | One worst loss is a single point. The average drawdown is the distribution you size to. |
The full station, every article in reading order: I · Foundations.
II · Market architecture
where edges live: underlying markets × instruments, two different axes
The market is the thing whose price you care about. The wrapper is the contract you hold: spot, forward, future, perpetual, ETF, CFD. Four ways to be long bitcoin are one view and four P&Ls. Spot has custody. A quarterly future makes you pay or earn the basis every roll. A spot ETF sleeps while bitcoin does not. A perpetual never expires, and the crowded side pays funding, about 11% a year when the 8-hour print is 0.01%, and much more in a mania. In April 2020, spot oil recovered from the negative print. Holders of the rolled-futures wrapper did not get that recovery back. Being right about the market and wrong about the wrapper still loses the money.
| Article | Why it is on this row |
|---|---|
| How FX PnL Actually Works | The pair, the account currency, and the roll are three different numbers. The backtest on a clean mid misses two of them. |
| Market Orders vs Limit Orders in FX | The order type chooses who pays the spread. That choice belongs in the strategy. |
| Why Bid/Ask Bounce Matters for Intraday FX Systems | On a short horizon the bounce is a large fraction of the move you think you forecast. |
| Currency Quoting Conventions: Numerator, Denominator, and the Priority Order | Which currency is the price, and which is the thing priced, changes the sign of every feature you build. |
The full station, every article in reading order: II · Market architecture.
III · Market theory
how markets can work in principle, efficiency is the null hypothesis
Events arrive in bursts. Volatility clusters. A liquidity shock can rewire correlations inside an afternoon. Clock time treats those as evenly spaced samples, and a lot of the structure lives in the waiting time, the path between prints, and the shape of the book of correlations. The articles here are frontier reading: they assume you already know what a null is, what a feature is, and what a cost line is. Read them cold and you collect vocabulary. Vocabulary does not size a position.
| Article | Why it is on this row |
|---|---|
| Market Data Is Social Data: From Fractals to Topological Data Analysis | The cross-section has a shape. Persistent homology is one way to measure when that shape tears. |
| The Omori Law: Why Aftershocks Follow Market Crashes | After a crash the intensity of large moves decays in a way you can fit. The clock for that decay is event time. |
| Long-Range Dependence: Real Memory or Just Short-Range Echo? | A slow autocorrelation can be real memory or a short-memory process with a break. The distinction changes the forecast. |
| Markets Are Getting More Random: Non-Stationarity of Randomness Itself | The amount of structure is a time series. A rule fit to a structured decade meets a noisier one. |
The full station, every article in reading order: III · Market theory.
IV · Edge mechanisms
why should an edge exist?, the root question of the map
Name the payer before you name the indicator. Reachable money is usually a risk someone better-resourced refuses to warehouse, a capacity limit that makes the trade a rounding error for them, or a flow that has to deal. A $5 million niche earning 40% a year is a living at your size and 0.01% of a $20 billion fund, which is why the fund leaves it. If the answer to "why does this pay" is "the backtest went up," you do not have a mechanism yet.
| Article | Why it is on this row |
|---|---|
| The Theory of Edge: Why the Market Pays You | Two checks: why you make money, and why you keep it. The barrier is measured against the participant across from you. |
| Who Is the Marginal Buyer? | Price is the last clip. If you cannot name who bids here, nothing is under the print. |
| Large Trades Are Insider Trades by Definition | Impact scales near the square root of size. The part that does not revert is the information. |
| Predictive Power vs Long Bias: The Hidden Trap in Backtests | A QQQ trend rule's 22% split into about 16% equity drift, 5% tech tilt, and 1% timing. |
The full station, every article in reading order: IV · Edge mechanisms.
V · Observable world
what can we measure?, point-in-time, or it does not exist
An observable is whatever was knowable then: price, a rate, funding, open interest, a commitment-of-traders print, the book. A revised series, a delisting filled in later, a hedge ratio fit on the whole sample, none of those existed that morning. Point-in-time is the filter. If the series fails it, the feature you build on top is a look at the answer.
| Article | Why it is on this row |
|---|---|
| Noise Is Not Volatility | Two paths with the same range can be a trend or a chop. The efficiency ratio separates them: net move over path length. |
| Efficiency Ratio Explained for Traders | The number, 0 to 1, that tells you whether the market you are about to trade is the kind your rule wants. |
| How to Rank Markets by Trend Quality | Rank the universe by the observable before you drop one system on all of them. |
| Reading the COT Report: Three Trader Groups, One Edge | Positioning is public, weekly, and late. The lag is why a slow account can still use it. |
The full station, every article in reading order: V · Observable world.
VI · Feature engineering
transforms of observable state, one raw variable, many research questions
One raw series supports many questions, and they are different hypotheses. Carry level asks how big the paycheck is. Carry over volatility asks how big it is per unit of pain. Carry rank asks whether this pair is the best paid in the set. Carry change asks whether the gap is widening. Carry conditioned on trend asks whether price already agrees. Five features, two rates and a spot. RSI, MACD, and a stochastic on the same close are often one band agreeing with itself. Stacking them feels like confirmation. The frequency response says it is one feature in costume.
The filter shelf past this table is the same question asked of one operator: which band it keeps, and how late. Butterworth, sinc, Hilbert, roofing, and the named oscillators are later visits. Start with the primer and the frequency response. A filter output is a feature. The forecast is a later station.
| Article | Why it is on this row |
|---|---|
| The Indicator Is More Important Than the Model | No transform of a weak input carries more information about the target than the input did. The ceiling is the feature. |
| Why Most Indicators Should Be Transformed Before Modeling | Scale, tails, stationarity, and cross-market units. The transform is part of the feature's name, and its window is not a backtest knob. |
| Feature Engineering Before Machine Learning | On daily bars the sample is small and the signal is thin. The pipeline that stationarizes and checks the histogram does more than the model swap. |
| No Filter Is Predictive: What Traders Misunderstand About Smoothing | A causal filter is a function of the past. A crossover is the moment the less-lagged average caught up, after the turn. |
The full station, every article in reading order: VI · Feature engineering.
VII · Hypothesis
“if mechanism X is real, feature F should predict Y over horizon H”
Write the death condition before the run. "Ranked by carry-to-volatility, the top third of G10 beats the bottom third over the next one to three months, after costs" can die: the buckets fail to rise in order, or the whole result lives in 2002 to 2007. "This chart looks like a head and shoulders" cannot die. Explanation is cheap after the print. A prediction is a dated, specific claim you cannot edit. The scientific bar is the pre-commit: hypothesis, null, statistic, threshold, held-out window, trial count, in a file whose timestamp is earlier than the result.
| Article | Why it is on this row |
|---|---|
| Technical Analysis as a Scientific Hypothesis | The rule, the statistic, the null, the threshold, written first. A popular moving-average cross on SPX often fails to clear 0.05. |
| How to Make Technical Analysis Falsifiable | Turn the pattern into a function, a horizon, a success count, and a baseline. Then publish the rejection. |
| The Null Hypothesis for Trading Systems | Start from "no predictive power on detrended data." A rule that has not beaten that is a candidate. |
| The Difference Between Explanation and Prediction in Markets | A story fitted after the close had the answer. A forecast did not. Keep a dated log if you want the second. |
The full station, every article in reading order: VII · Hypothesis.
VIII · Validation
is it real, and does it survive costs?, most ideas die here, and that is the point
Most ideas die here, and the archive is the output. A single Sharpe is a sample statistic with a wide interval: a Sharpe near 1 on a few years of daily data is often consistent with a true Sharpe near 0. The best of forty-one thresholds is a maximum. At a 5% bar the family-wise false-positive rate on that scan is about 88% before you correct it. Add the spread, the fees, and an honest slippage before you like the curve. A printed machine-learning paper can fail on its own numbers: a do-nothing baseline, a base rate, a cost line that was never subtracted.
| Article | Why it is on this row |
|---|---|
| Why One Backtest Tells You Almost Nothing | Report the interval. A 12% annualized mean on a noisy daily sample can have a 95% band that includes a loss. |
| Backtesting Is an Experiment, Not a Screenshot | Pre-commit, detrend, permute, correct for the number of tries. One equity curve is one draw. |
| CSCV: A Direct Probability of Backtest Overfit | The probability that the in-sample winner is a loser out of sample, computed from the search you ran. |
| Permutation Tests for Indicator Significance | Shuffle the target, rerun the whole scan, and compare your best statistic to the best of each shuffle. |
The full station, every article in reading order: VIII · Validation.
IX · Forecast / signal
a statement about the future, not a trade yet
AUDJPY at +1.3 and EURCHF at −0.8 are comparable units, and neither is a position. The station is the map from feature to expected value; in a cross-section, the stronger version is often an order, not a number.
| Article | Why it is on this row |
|---|---|
| Ranking Beats Forecasting for Many Trading Problems | The cross-section often needs an order. Rank, then hold the wings. |
| Ranking Beats Forecasting — But Ranking What? | The target you rank on decides the trade. A rank of the wrong residual is a clean sort of noise. |
| From Indicator Value to Expected Value | Map the feature to a conditional expectation before you turn it into a position. A z-score still has to become an edge in currency units. |
The full station, every article in reading order: IX · Forecast / signal.
X · Decision policy
forecast → position: trade only if E[r] clears costs + threshold
The decision is the arithmetic after the score: expected edge next month, about a 4.1% gap divided by 12, near 34 basis points, against a couple of basis points to get in and out at institutional size. Clear the toll with room, then size by risk so one wild pair cannot own the book. Refuse a rule whose expected gross edge per trade sits under about three times the all-in round trip. That filter deletes most of what gets marketed as a five-minute system.
| Article | Why it is on this row |
|---|---|
| Expectancy: The Most Important Formula in Trading | Win rate times average win, minus loss rate times average loss. The tail term is the one the win rate hides. |
| Cost-Aware Ranking: The Missing Step in Cross-Sectional Strategies | A name that ranks first and costs 40 basis points to enter is a different trade from a name that ranks third and costs 2. |
| Why Transaction Costs Should Be Added Before You Fall in Love | Put the toll in the backtest on the first run. A curve you have already bonded with will argue for a kinder cost. |
| The Trader's Real Job: Control Losses, Not Predict Everything | Direction is the variable you do not set. Size, exposure, the drawdown stop, and the kill criterion are the ones you do. |
The full station, every article in reading order: X · Decision policy.
XI · Strategy
a decision rule repeated through time, and not everything that trades is alpha
A strategy is the decision frozen: monthly, rank by carry-to-vol, long the top three, short the bottom three, equal risk, rebalance. Morning mood is no longer an input. A clever way to buy is plumbing, a regime model is weather, and a risk limit is a seat belt. Useful, and none of them is a reason someone is paying you. High-noise markets want reversion. Low-noise markets want trend. One indicator on every chart is a refusal to read the observable.
| Article | Why it is on this row |
|---|---|
| The Difference Between a Trading Rule, a Strategy, and a Portfolio | A rule emits a score. A strategy adds size, a vol target, and a kill. A portfolio is the set of strategies that can survive one of them dying. |
| Trading Systems Are Recipes, Not Predictions | Precise enough that a stranger gets your trades on your data. The recipe includes the kill, because the regime the recipe assumes will end. |
| Matching Strategy Families to Market Conditions | Family first: trend, reversion, carry, breakout. The market's noise level picks the family. |
| High Noise Markets Are Mean-Reversion Markets | Path length long relative to net move. Fading is the family that matches the observable. |
The full station, every article in reading order: XI · Strategy.
XII · Factors
the same mechanism, systematically, across an entire universe
Factors come after one asset works end to end. A carry factor is the same question asked of every pair: high carry against low carry, and you no longer care whether AUDJPY rises.
| Article | Why it is on this row |
|---|---|
| What Is a Factor, Really | The same mechanism, applied to a universe, long the high slice and short the low slice. |
| What a Factor Actually Is: α + βλ, and Why the Market Is Factor #1 | Split the return into the market, the premia you are paid to hold, and a residual. Sell the residual last. |
| Predict Residual Returns, Not Gross | Gross return smuggles the beta. The thing you meant to forecast is what is left after the factor exposures. |
| Portfolio Sorts From Scratch: Deciles, Monotonicity, and the Long-Short Spread | Buckets have to rise in order. The long-short spread is the claim. A pretty top decile with a messy middle is a story. |
The full station, every article in reading order: XII · Factors.
XIII · Multi-factor models
composites: carry + momentum + value, regime-conditioned
Composition reopens the search. A leftover alpha in a regression is often a factor you left out. A zoo of published factors is a counted search; the t-stat you remember was the maximum of many tries. Timing the factors, turning them on and off with a second model, mostly fails once you count that second search. Cross-sectional machine learning, in the study that measured it carefully, lifts about 20%.
| Article | Why it is on this row |
|---|---|
| The GRS Test: Your Alpha Is Probably a Missing Factor | A joint test on whether the leftovers are all zero. One shiny intercept is a single name in that test. |
| Fama-MacBeth Two-Pass and the Shanken Correction Nobody Applies | Cross-sectional slopes, then the error in those slopes. Skipping the correction makes the t-stats look finished. |
| The Factor Zoo and the Multiple-Testing Reckoning | Hundreds of published factors, one history. The bar moves once you count the tries. |
| Factor Timing Mostly Fails — the Honest Version | A second model that switches factors reopens the search. Most of the switching does not survive it. |
The full station, every article in reading order: XIII · Multi-factor models.
XIV · Alpha ensembles
combining edges into one forecast engine
Two edges with a Sharpe near 0.5, roughly uncorrelated, combine to about 0.5 times the square root of 2, near 0.7. Five copies of the same idea, correlation 0.85, give you almost nothing and one decay date.
| Article | Why it is on this row |
|---|---|
| The Death of the Single-System Trader | One rule is one decay away from a multi-year sideways grind. A handful of structurally different systems is the comparison set. |
| Signal Averaging: Killing Noise with Redundant Alphas | Average signals that share a mechanism and differ in noise. Averaging five paraphrases of one price series does not. |
| Don't Trust Your Strategy-Weighting Scheme | The scheme that maximized in-sample Sharpe is another search. Flat risk weights are the baseline it has to beat. |
The full station, every article in reading order: XIV · Alpha ensembles.
XV · Portfolio construction
from forecasts to risk: budget it, do not just add it
Budget a portfolio volatility, cut every position when realized vol doubles, cap one name's share of risk, and write the drawdown rule before the drawdown. Signal quality and portfolio quality come apart: a real signal with the wrong weights is a bad portfolio. Overbetting is the failure mode the Kelly fraction exists to refuse.
| Article | Why it is on this row |
|---|---|
| Why Volatility-Adjusted Position Sizing Matters | Size to risk. Equal vol contribution stops one pair owning the book. |
| Why Portfolio Construction Is Part of the Signal | The weights change the equity curve as much as the forecast does. Treat them as part of the recipe. |
| The Difference Between Signal Quality and Portfolio Quality | A good score and a good book fail for different reasons. Diagnose the layer you broke. |
| Drawdown Is Not Just a Number: It Is a Diagnosis | Depth, length, and whether the other systems are fine. Those three say different things. |
The full station, every article in reading order: XV · Portfolio construction.
XVI · Implementation
where paper alpha meets the market
On Hyperliquid BTC in a studied window, a refused post-only buy returned about 0.31 basis points over ten seconds. The taker fee sat around 1.44 to 2.7 basis points. Stand aside as a taker; the edge does not clear the toll. Markouts are the truth serum: where the mid is a short time after you filled. Your own size walks the book at something near the square root of the fraction of volume you took. A simulation that fills you at mid, with no queue and no clock drift, is a different market from the one that sends the reject.
| Article | Why it is on this row |
|---|---|
| Five Definitions of Fair Value, and the Trade Each One Implies | Name the subtraction before the trade. If the forecast is inside the fee, there is no trade. |
| Markouts: The Truth Serum of Market Making | Mark the fill against the mid a fixed time later. The backtest mark is a story you told yourself. |
| Adverse Selection Explained for Traders | The flow that hits your quote knew something. The spread is the rent you charge for that. |
| Adverse Selection Is Adverse Selection: Porting Fast-Fills-Are-Bad-Fills to FX and Futures | The fast fill is the toxic one in FX and futures too. |
The full station, every article in reading order: XVI · Implementation.
XVII · Live research
strategies are mortal, monitor, adapt, retire
The live rule is an experiment that does not end. Watch the paycheck (the gap can close because policy changed), the crowding (positioning stretched means a narrow exit), and the weather. Two exits are both legitimate. Adapt: go back to the mechanism, the observable, and the feature with what the break taught you. Retire: archive the rule with a post-mortem so the next version of you does not pay the tuition twice. A crowded edge grinding lower as the trade gets popular does not heal by waiting. A barriered edge inside a historical-looking drawdown is often noise. The difference is the diagnosis, and it has to be written before you are in the drawdown.
| Article | Why it is on this row |
|---|---|
| How to Detect When a Trading System Is Dying | Decay is usually a grind. You need a measure that fires before the equity curve feels wrong. |
| When to Switch Off a Trading System | The kill criterion is a number you set on a calm day: drawdown, hit rate over a counted window, or a structural breach. |
| Why Systems Work Until They Don't | The rule was conditional on a regime. The post-mortem names which condition ended. |
| Why OOS Failure Is Often a Stationarity Failure | The held-out window failed because the distribution moved. |
The full station, every article in reading order: XVII · Live research.
The two rings (and where ML sits)
Two conditions wrap every station of the spine.
The regime / state ring
which market are you in today?
The same carry rule is an income stream in calm markets and a crash in a yen squeeze. Into August 2024 the Bank of Japan lifted rates to about a quarter of a percent, USDJPY fell from about 162 to about 142 in weeks, and the Nikkei dropped about 12% in a day. The mechanism was intact. The weather had changed. A backtest that lived inside one regime is a sample of that weather. Regime conditions the feature, the forecast, and the size at once.
| Article | Why it is on this row |
|---|---|
| Stationarity: The Word Every Trader Ignores Until It Kills the Strategy | Yesterday's conditional distribution is the thing the live rule is betting still holds. |
| Slow Wandering: The Most Dangerous Type of Market Change | The quiet multi-year drift kills more rules than the crash you can see on a chart. |
| Volatility Regimes and Strategy Survival | Vol is more regime than trend is. A rule sized to one vol state meets the next one oversized. |
| Regime Coverage: Why Your Backtest Needs Different Market States | One friendly decade is one state. Coverage means the hostile states are in the sample on purpose. |
| Why Market Cycles Are Evanescent | A measured cycle drifts, fades, and loses phase. A hardcoded period is a bet that this one stays. |
| Correlation Regimes: Positive Feedback, Breakdowns, and "USDCAD Is the Truth" | The hedge you wrote in one correlation regime is a different position after the break. |
| Mutual Information as a Regime / Noise Filter | Use dependence as a gate on when the rule is allowed to trade. |
| Entropy as a Market Choppiness Gauge | Choppiness you can compute is a regime input. A flat periodogram is the rule standing down. |
The research governance ring
is the research telling the truth?
Governance polices every arrow between the stations. Before the run: the hypothesis, the null, the benchmark, the number of trials, the point-in-time rule, and the result that would kill it. A parameter that works only at 13 and fails from 11 to 17 memorized the sample. A loose region, Sharpe stable across a band, is the one you can defend. Simplicity is the degrees-of-freedom cap: effective sample size in markets is a few hundred independent bets, and each free parameter spends some of them.
| Article | Why it is on this row |
|---|---|
| Why "Quantitative" Does Not Automatically Mean Scientific | A falsifiable claim, a null, a benchmark, and a rerun. Those four are the method. |
| The 10% Rule of Degrees of Freedom | Cap free parameters near a tenth of the sample. The search space grows as the product of the knobs. |
| Degrees of Freedom in Trading Systems | Every threshold, lookback, and market you kept after looking is a trial. Count them. |
| Loose Pants Fit Everyone: Why General Trading Ideas Survive Longer | Robustness ratio: scatter of Sharpe across the sweep, divided by the mean. A spike at one setting is a tailored fit. |
| Why Simplicity Is a Statistical Weapon | Added parameters fit noise in sample. Out of sample they spend the edge they appeared to add. |
| Why Benchmarks Matter in Rule Evaluation | 15% a year against zero and 15% against a bias-matched random rule are different claims. |
| The Problem with One Sample of Market History | Resampling shrinks the inner error. It does not give you a second history. Size for that. |
| The Red-Flag Field Guide: How to Spot a Fake ML Trading Paper | Printed accuracy, a missing cost, a base rate, a copied table. The failure is usually on the page. |
| Read the Paper for Its One Load-Bearing Number | One figure has to survive contact with the abstract. Find it before you discuss the architecture. |
| Replication Notebook Template: Claim, Replicate, Stress, Verdict | The shape of a check: the claim, the rerun, the stress, the verdict. Archive the dead ones. |
| Building a Statistically Valid Backtest: The Checklist Nobody Runs | Published predictors run about 26% weaker out of sample and 58% weaker after print. The list is a frozen holdout, a cost, a size cap, and a test of the whole set. |
| The Vice of Complexity: Four Times the Simple Model Won | 12,000 features on 12 months. The re-estimated complex book earns a Sharpe of 0.49, and the small fit is the one that clears the next window. |
Where machine learning sits
A fitted model weights and conditions signals that already have a payer. "I trained XGBoost" is a method. The mechanism is still the question in the first section. On this site the fit shows up late: after the feature is stationary, after the band is named, after the null exists. Trees will spend their splits on a raw price level and call it skill. Regularization is the complexity penalty you can write down. Below a few minutes the function class can matter; above an hour the feature usually matters more. A model that only works as an interaction still has to clear costs as a trade.
| Article | Why it is on this row |
|---|---|
| The Limits of Linear Models | Linear is the baseline the nonlinear fit has to beat on a held-out window, after costs. |
| Linear Models' Hidden Symmetry Advantage | A linear fit has a constraint the tree does not. Sometimes the constraint is the robustness. |
| From One Tree to Forests to Boosting | The ensemble averages trees. It does not average away a leaked label or a non-stationary input. |
| How a Decision Tree Engineers a New Alpha | The splits are a feature constructor. Read the leaves as a rule, and count the trials. |
| Ridge Above 1h, XGBoost Below 5min | Horizon picks the function class. A five-minute booster on a daily fundamental is a costume. |
| Regularization from First Principles | The penalty is a degrees-of-freedom cap with a dial. Set the dial outside the backtest you are grading. |
| Does ML Actually Help Asset Pricing? Kelly's 20%, Not 2–3× | About 20% lift in the cross-section, in the study that tried to measure the help. That is the scale. |
| Predictive but Uncorrelated: Alphas That Only Work as Interactions | A feature with no standalone correlation can still matter inside a product. Test the product, and pay its turnover. |
The markets
The map walks fourteen markets and the instrument layer on top of them. One family gets its own shelf here: prediction markets, where a fair book is arithmetic you can check.
Alternative / event markets
On a prediction market the cleanest money is a book that cannot all happen at once: two contracts that each look fair and together cost more or less than the certain payoff. That is a Dutch book, and the trade is a projection back onto the set of prices that add up. Forecasting the event is further down the list, and it is the edge that crowds fastest. The same spine still applies. Who pays, what you could have measured, what would kill it, whether the fill clears the fee. A copied arbitrage that crosses the spread is a different trade from the one the detector saw.
| Article | Why it is on this row |
|---|---|
| The Nine Sources of Edge, Ranked Cleanest to Dirtiest | Structural inconsistency at the clean end. A forecast of the outcome at the dirty end. Start at the clean end. |
| The Dutch Book Theorem, Plainly, and Why Polymarket Will Always Have Arbitrage | Prices that violate addition are a locked payoff. The venue's matching does not close every one of them. |
| Outcome Geometry: Why Two Fair Markets Can Be Jointly Unfair | Each margin can look sane. The joint book is the object that has to be fair. |
| The Marginal Polytope: One Shape That Contains Every Fair Price | The allowed prices are a shape. A quote outside it is the trade. |
| Arbitrage Is Just Projection: One Calculation Gives Trade, Profit, and Target Prices | One projection gives the basket, the profit, and the prices you are pushing toward. |
| The Six Ways to Lose Money on Polymarket | Resolution, fees, missed fills, and sizing take the money even when the inconsistency was real. |
| A Good Trade Is Not a Correct Prediction — The Five Invariants | The trade can be right about the book and wrong about the world, and still be the trade you meant. |
| Who Profits From Prediction? Execution, Not Information | On the published flow, the profit sits with the account that got filled. |
Playing a different game: the retail edge
Game selection beats skill. A small account has real advantages, and none of them is speed.
Which table can this account win?
One taker round trip a day at 10 basis points costs about 25% a year (252 times 10 basis points). Ten a day costs 252%, before the rule has earned a dollar. Latency games, market making on major venues, and reacting to a scheduled print put you across from a machine that saw it first and pays a fraction of your fee. The tables a small account can win are the ones where patience, a tiny capacity, and a public calendar matter, and speed does not: days to months, neglected names, funding you can collect, pre-announced rebalances. Boredom is the cheap toll. A prop-firm fee is a product. Read the daily-loss rule as a sizing constraint before you pay it.
| Article | Why it is on this row |
|---|---|
| Why Traders Lose Even When Their Ideas Are Good | Seven layers between a signal and live P&L. Costs, a 30-trade sample, and long-bias drift each take a cut. |
| Prop Firm Math: Edge, Barriers, and Cash After the Fee | The fee, the daily loss cap, and the deadline are the game. Pass the sizing arithmetic before the challenge. |
| Maker vs Taker Edge: Same Signal, Different Economics | The same signal can be worthless when you pay the spread and useful when you earn it. |
| Why Small Alphas Matter More for Makers Than Takers | A small edge that fails as a take can pay as a quote improvement. |
| FX Is Not One Market: Retail vs Wholesale Structure | Retail and interbank are different products. The broker's routing is part of the signal's economics. |
| Why Retail FX Execution Is Not the Same as Interbank FX | The overnight financing on a retail roll can eat the carry you came for. Measure your swap against the rate gap. |
| MFT Execution Is Built on HFT Market-Making | Your "fast" on a major book is someone else's leftover. The horizon decides whether that matters. |
| Match Your Edge to Your Resources | Rank the edge by what you have: data, speed, capital, patience. A mismatch is a donated table. |
| Why Good Trading Feels Boring | A 10% vol target on $100,000 is about $630 of daily noise. If the P&L is entertaining, the size is the entertainment. |
Take the map with you
The spine, the two rings, fourteen markets, five worked descents, and a library of about 835 strategy entries, each with a named payer and a named failure mode, in one 65-page PDF. The grand-map plate inside is vector at A2. Print that page for the wall and read the rest as a booklet. The tables above are rows of that library written out in full; the PDF tells you which rows to want next.